A sunlit terrace above the Thames in London: three tall glass panes framing a workshop, a townhouse and a meeting, a ribbon of ivory light coiled on the marble floor and flowing towards the river, Tower Bridge beyond.

Click the film to pause or playTap the film to pause or play back or forward 10 seconds

Succession Liquidity

What Is Succession Liquidity?

Succession liquidity is the accessible capital a family needs at the moment succession occurs — to meet taxes, debts, buyouts and a fair distribution among heirs — without being forced to sell, refinance or restructure assets under pressure.

When Does It Become a Problem?

Different situations. One common challenge: the need for liquidity at the right time.
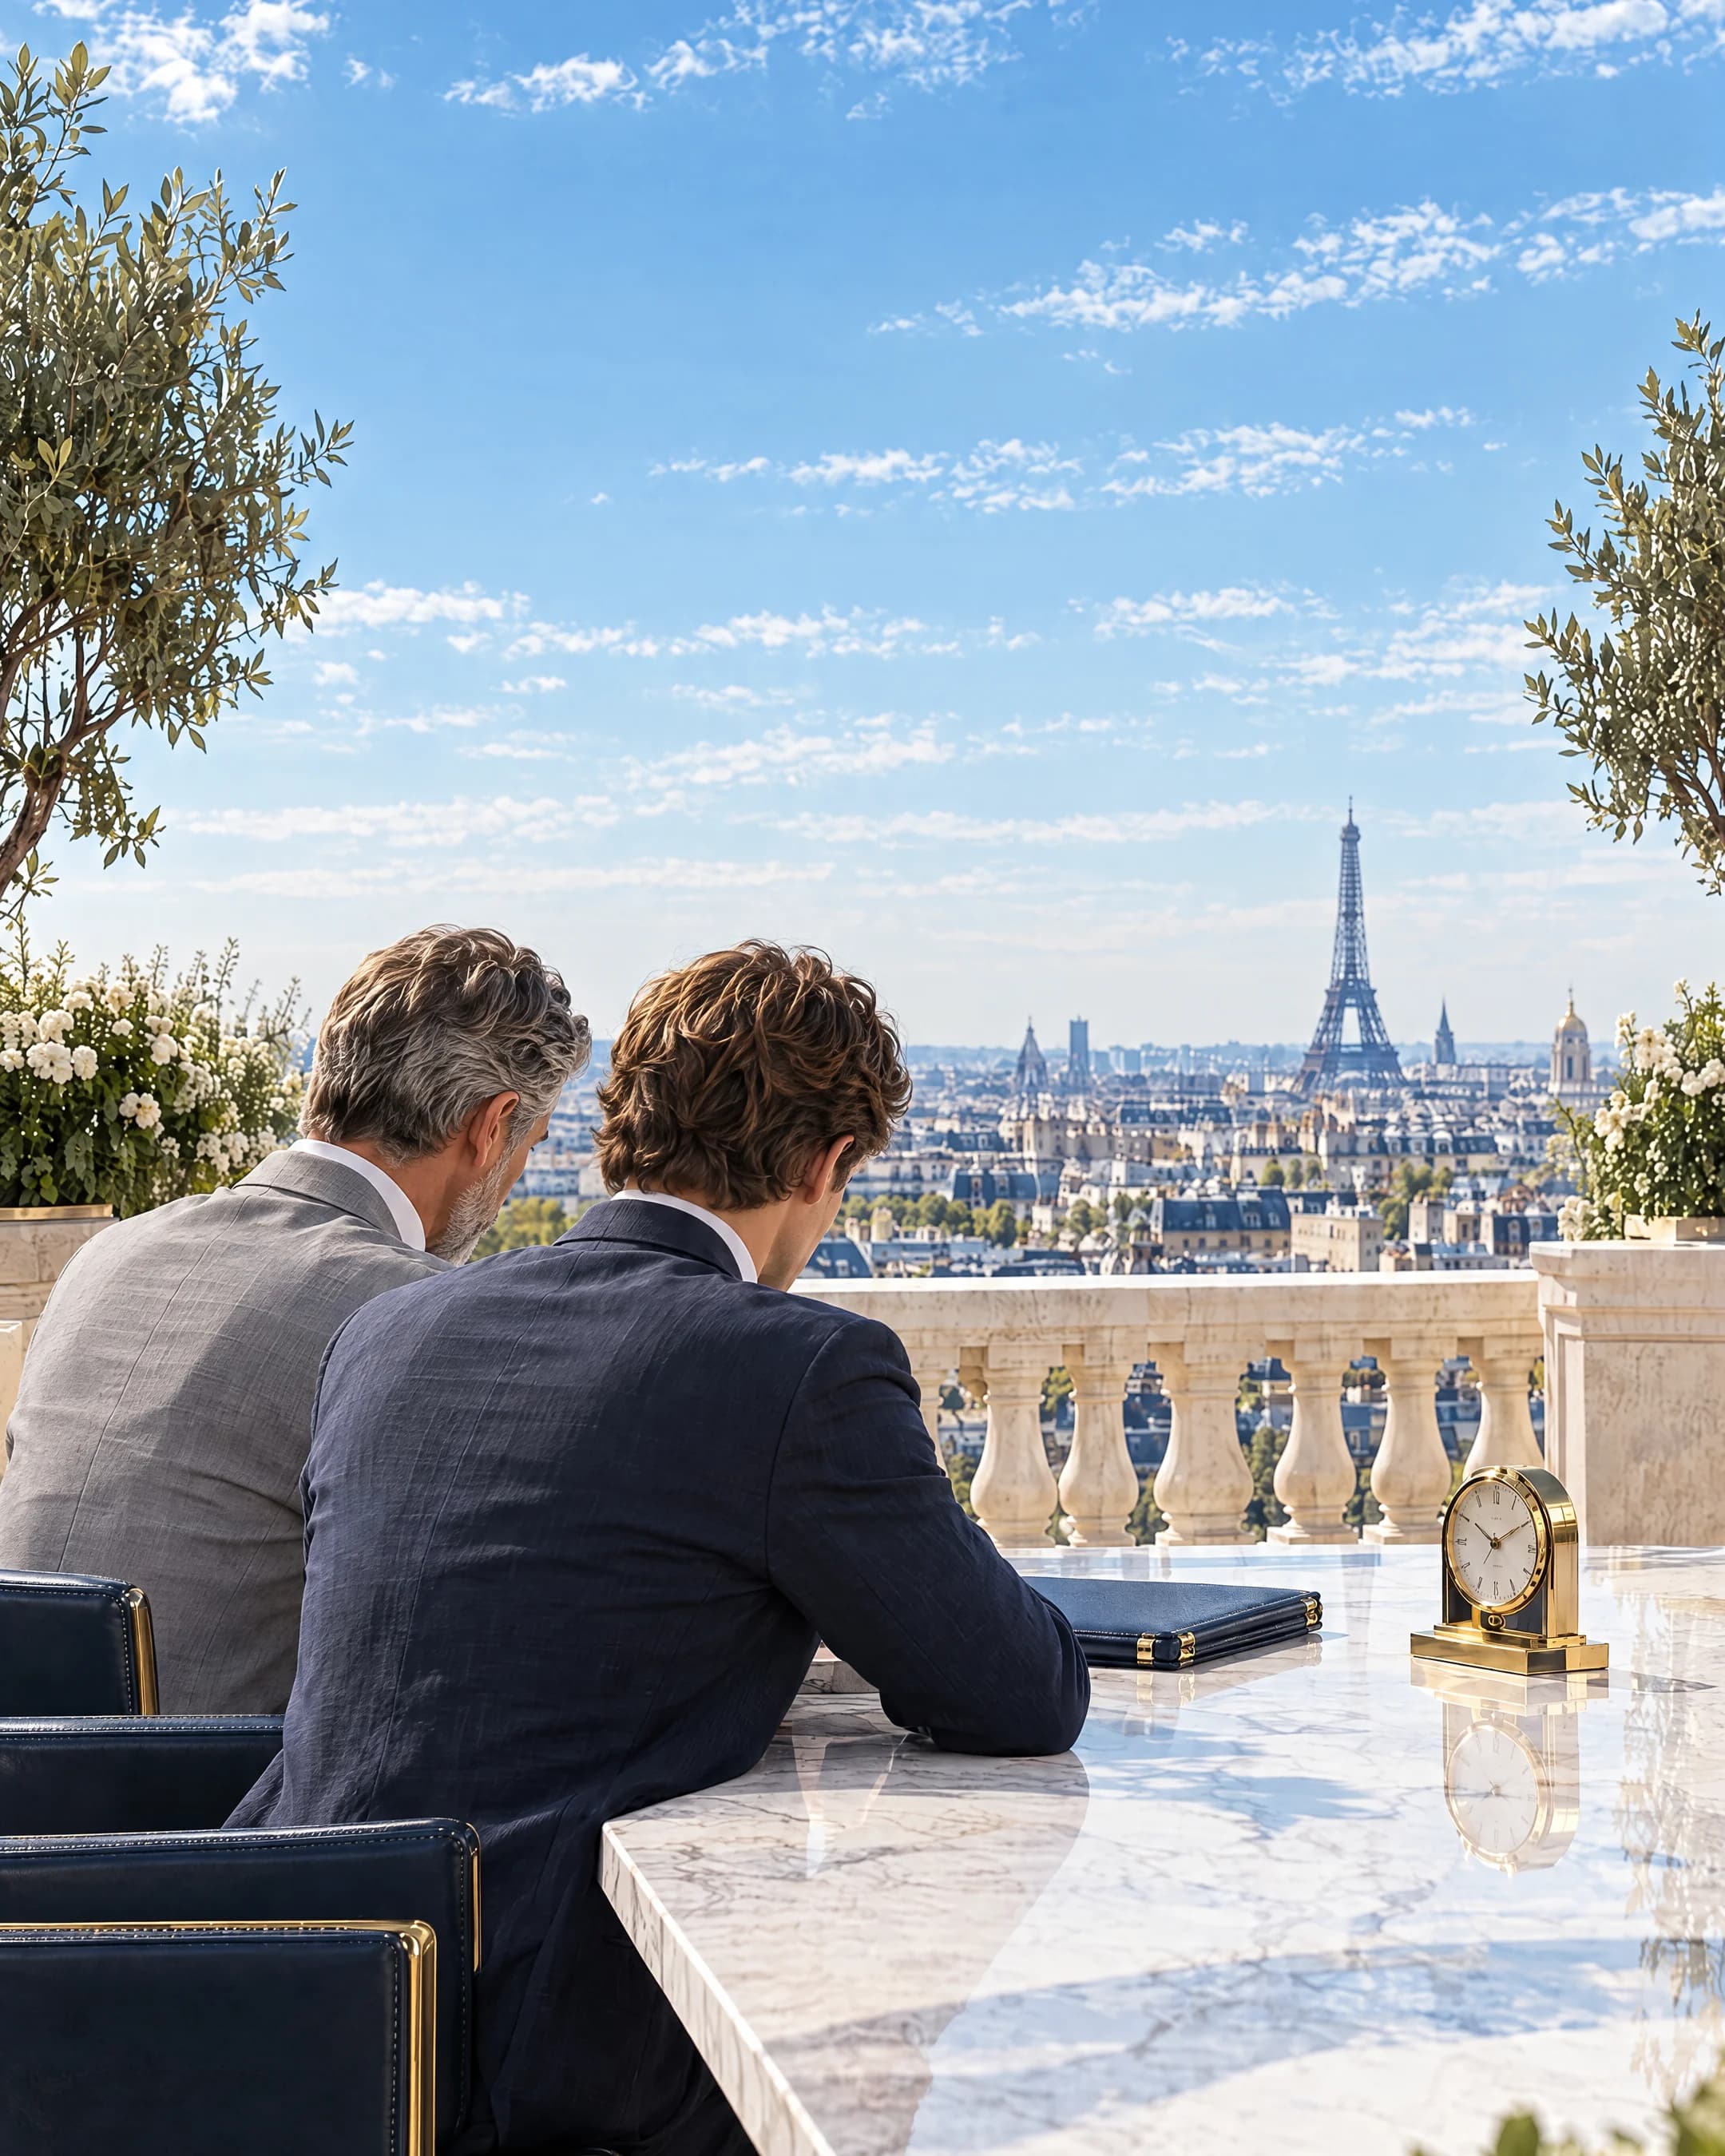
  • On a sunlit Paris terrace, an heir and his adviser, seen from behind, sit at a marble table with a navy folio and a brass desk clock, the Eiffel Tower beyond.

    Case 01Inheritance Tax

    When obligations arrive before liquidity.

    Inheritance Tax can create a liquidity requirement at the same time wealth is transferring. Even when the value exists, the cash needed to meet the obligation may not. Preparing liquidity in advance can reduce financial pressure during succession.

    Explore the case
  • In a private bank's sunlit meeting room high above London and St Paul's, a navy leather credit folio with a brass pen ready to sign, a brass seal, and a scale model of a family's stone building in a glass case.

    Case 02Bank Facilities & Personal Guarantees

    When the founder is no longer there, the exposure remains.

    Bank facilities and personal guarantees may be linked to the founder’s financial profile, collateral or banking relationships. During succession, these arrangements may be reassessed, creating a liquidity need to manage debt, guarantees or refinancing without unnecessary pressure.

    Explore the case
  • In a sunlit boardroom above the Gulf skyline, a white scale model of the family's working business, factory halls, delivery trucks and offices, in a glass vitrine fed by a glass tank of water, with a navy leather folio and a brass key in front of it.

    Case 03Business Continuity & Buyout Funding

    When succession requires funding — not only a plan.

    When ownership and management are changing, the business still needs to operate. Liquidity may be required to support working capital, fund a buyout or reorganize ownership, helping preserve continuity without forcing the sale of important assets.

    Explore the case
  • Three siblings stand at a glass vitrine holding a model of the family estate, on a marble terrace facing New York.

    Case 04Family Equalization & Fair Distribution

    When fairness matters, but assets are not easily divided.

    Family wealth is rarely easy to divide. Liquidity can help balance value between family members when businesses, property or other assets cannot be divided practically, while respecting the founder’s intentions and the legal or Sharia framework that applies.

    Explore the case
How Riches & Guards Helps

From financial structure to succession liquidity.

A structured approachfor a more certain tomorrow.
Navy leather ledgers with a brass loupe and a fountain pen on a sunlit marble desk, Lake Geneva and its fountain beyond the terrace.
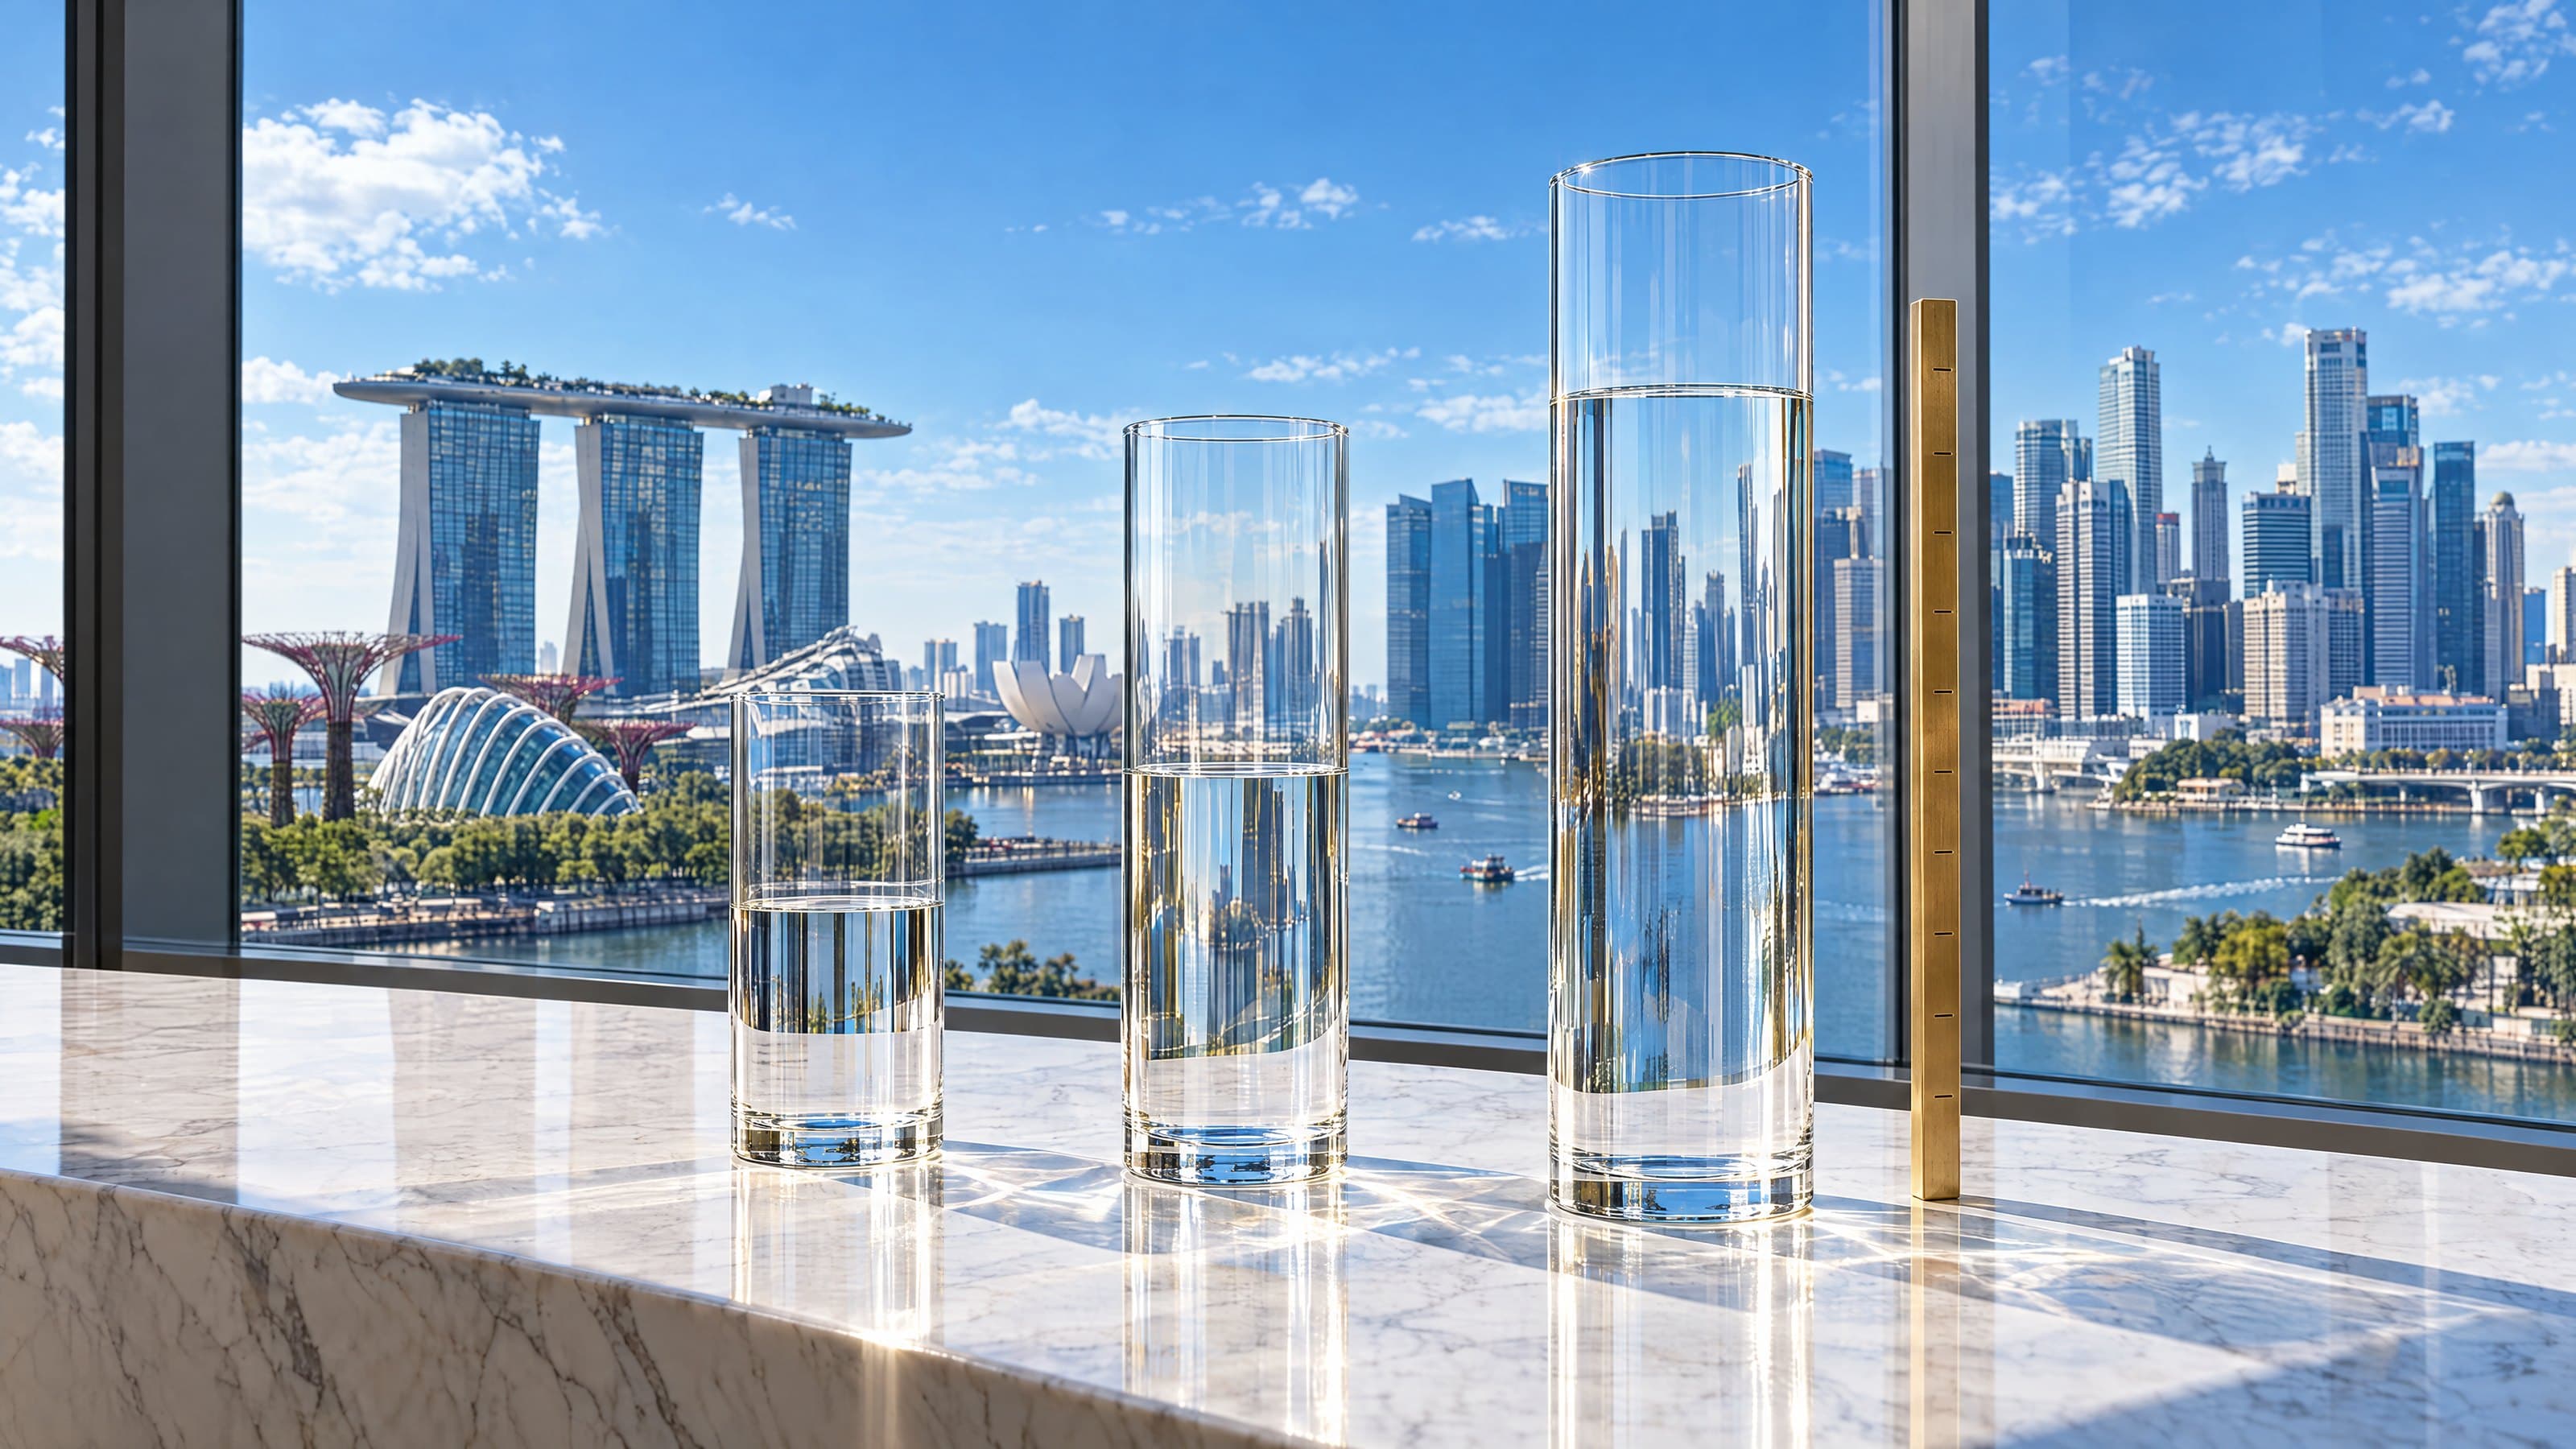
Three glass cylinders of clear water at different levels beside a brass rule on a sunlit marble ledge, Singapore's skyline beyond the window.
A glass-and-brass model of an arched bridge between two marble blocks, with a rolled drawing and a brass compass, London and St Paul's beyond the terrace.
An empty marble table laid with five navy folios and pens, five leather chairs around it, Manhattan's skyline beyond the windows.
  1. Navy leather ledgers with a brass loupe and a fountain pen on a sunlit marble desk, Lake Geneva and its fountain beyond the terrace.

    AssessUnderstand today

    Assess the Financial Structure

    We review the client’s assets, liabilities, ownership structures, bank facilities, personal guarantees and existing arrangements in the context of succession.

    • Assets and major holdings
    • Liabilities and debt
    • Ownership structures
    • Bank facilities and guarantees
    • Existing liquidity and family arrangements
  2. Three glass cylinders of clear water at different levels beside a brass rule on a sunlit marble ledge, Singapore's skyline beyond the window.

    QuantifyClarity for tomorrow

    Quantify the Liquidity Need

    We assess where liquidity may be required, how much may be needed and when it may be needed — including potential tax obligations, debt, buyouts, business continuity and family equalization.

    • Inheritance tax
    • Debt obligations
    • Buyout funding
    • Timing
    • Amount needed
  3. A glass-and-brass model of an arched bridge between two marble blocks, with a rolled drawing and a brass compass, London and St Paul's beyond the terrace.

    DesignTurn plans into progress

    Design the Liquidity Strategy

    We design succession-liquidity strategies intended to deliver meaningful liquidity at the point it is needed, while using capital as efficiently as possible.

    • Capital-efficient solution design
    • Meaningful liquidity when needed
    • Implementation path
    • Next steps
  4. An empty marble table laid with five navy folios and pens, five leather chairs around it, Manhattan's skyline beyond the windows.

    CoordinateA united approach

    Coordinate With Existing Advisers

    We work alongside the professionals the family already trusts — including family offices, trustees, lawyers, tax advisers, private banks and other specialists — so the liquidity strategy fits within the wider succession plan.

    • Family offices
    • Trustees
    • Lawyers
    • Tax advisers
    • Private banks
    • Existing advisory structure

Assess the Financial Structure

Every family has a different financial structure, and the first step is to understand the parts that are relevant to the liquidity issue the founder wants to address.

The assessment does not necessarily need to cover the family’s entire wealth.

If the founder wants to focus on Inheritance Tax, bank facilities, business continuity, or another specific issue, the assessment can be limited to the assets, liabilities, ownership arrangements and financial obligations connected to that issue.

If the founder wants a broader view, the assessment can expand accordingly.

Within the agreed scope, we look at how the relevant assets and obligations are structured, where liquidity already exists, where value is held in less liquid assets, and how quickly that value can be accessed.

This gives us a clear financial picture of the specific issue before moving to the next step: defining the liquidity need.

Quantify the Liquidity Need

Understanding the financial structure tells us where value is held.

The next step is to determine how much liquidity may actually be required during succession.

That requirement can come from different sources: Inheritance Tax, banking obligations, business continuity, buyout requirements, family equalization, or other financial needs within the agreed scope.

We identify the relevant obligations, when they may arise, and how much liquidity may be required to meet them.

Timing is especially important.

A family may have substantial wealth, but if the required liquidity is needed before assets can be accessed, sold, refinanced or reorganized, a liquidity gap may still exist.

The objective is therefore not only to calculate an amount.

It is to understand the amount, the timing, and the purpose of the liquidity requirement.

In some situations, the available information allows the requirement to be quantified relatively clearly.

In others, future values, tax exposure, financing conditions or business circumstances may still be uncertain.

In those cases, the requirement may be assessed through ranges or different scenarios rather than a single fixed number.

This gives the founder a clearer picture of the potential liquidity exposure and provides the financial basis for the next stages of the strategy.

Design the Liquidity Strategy

Once the liquidity requirement has been identified, quantified and aligned with the relevant structure, the next step is to design the funding strategy.

The starting point is the need itself: how much liquidity may be required, when it may be needed, and what it needs to fund.

In most of the situations we work on, the founder does not need to hold the full future liquidity requirement in cash from today.

Instead, a measured capital commitment during the founder’s lifetime can be used to create a significantly larger pool of dedicated liquidity that becomes available when succession occurs.

Advanced life insurance instruments can play an important role in creating that future liquidity.

Depending on the structure, the founder may fund the strategy directly through premiums, or bank financing may be used to support part of the funding requirement where appropriate and available.

The purpose is to reduce the amount of capital the founder needs to commit directly today while still building a meaningful pool of future succession liquidity.

The exact structure depends on the founder’s circumstances, the size and timing of the liquidity requirement, underwriting, product terms, financing conditions and the liquidity already available.

The solution therefore does not start with a predetermined product.

The product and the financing structure, where financing is used, are selected after the actual liquidity requirement has been defined.

The objective is to use capital efficiently today while creating dedicated liquidity for the future, allowing a larger part of the founder’s wealth to remain invested in businesses, real estate and other productive assets.

Ultimately, the goal is to make sufficient liquidity available when succession occurs without requiring the founder to reserve the full amount in cash throughout his lifetime.

Coordinate With Existing Advisers

Most founders with substantial wealth already have advisers responsible for different parts of their financial and ownership structure.

Legal advisers may be responsible for ownership and succession arrangements. Tax advisers may assess the applicable tax position. Banks may manage financing and credit relationships. Trustees, family offices and other specialists may also have defined roles.

Riches & Guards does not replace these advisers.

Our role is focused on the liquidity dimension of succession.

Once the liquidity need has been identified, and with the founder’s approval, we coordinate the relevant financial requirements with the advisers involved in the agreed scope.

This helps us understand how the liquidity strategy needs to interact with the existing legal, tax, ownership and banking arrangements.

In some situations, the advisers may identify requirements or constraints that affect the amount, timing or structure of the liquidity solution.

In other situations, the liquidity analysis may highlight a funding issue that the founder wants the advisers to consider within their own areas of responsibility.

The objective is not to redesign the founder’s entire structure.

The objective is to make sure the liquidity strategy can work alongside the arrangements already in place and support the founder’s succession objectives from a financial perspective.

Riches & Guards complements the family’s existing advisory structure. We do not seek to replace it.

Depending on the family’s circumstances and the jurisdictions involved, a strategy may draw on established instruments, including life-insurance-based solutions held within appropriate structures. Any outcome depends on the terms of those instruments, their implementation and future events.
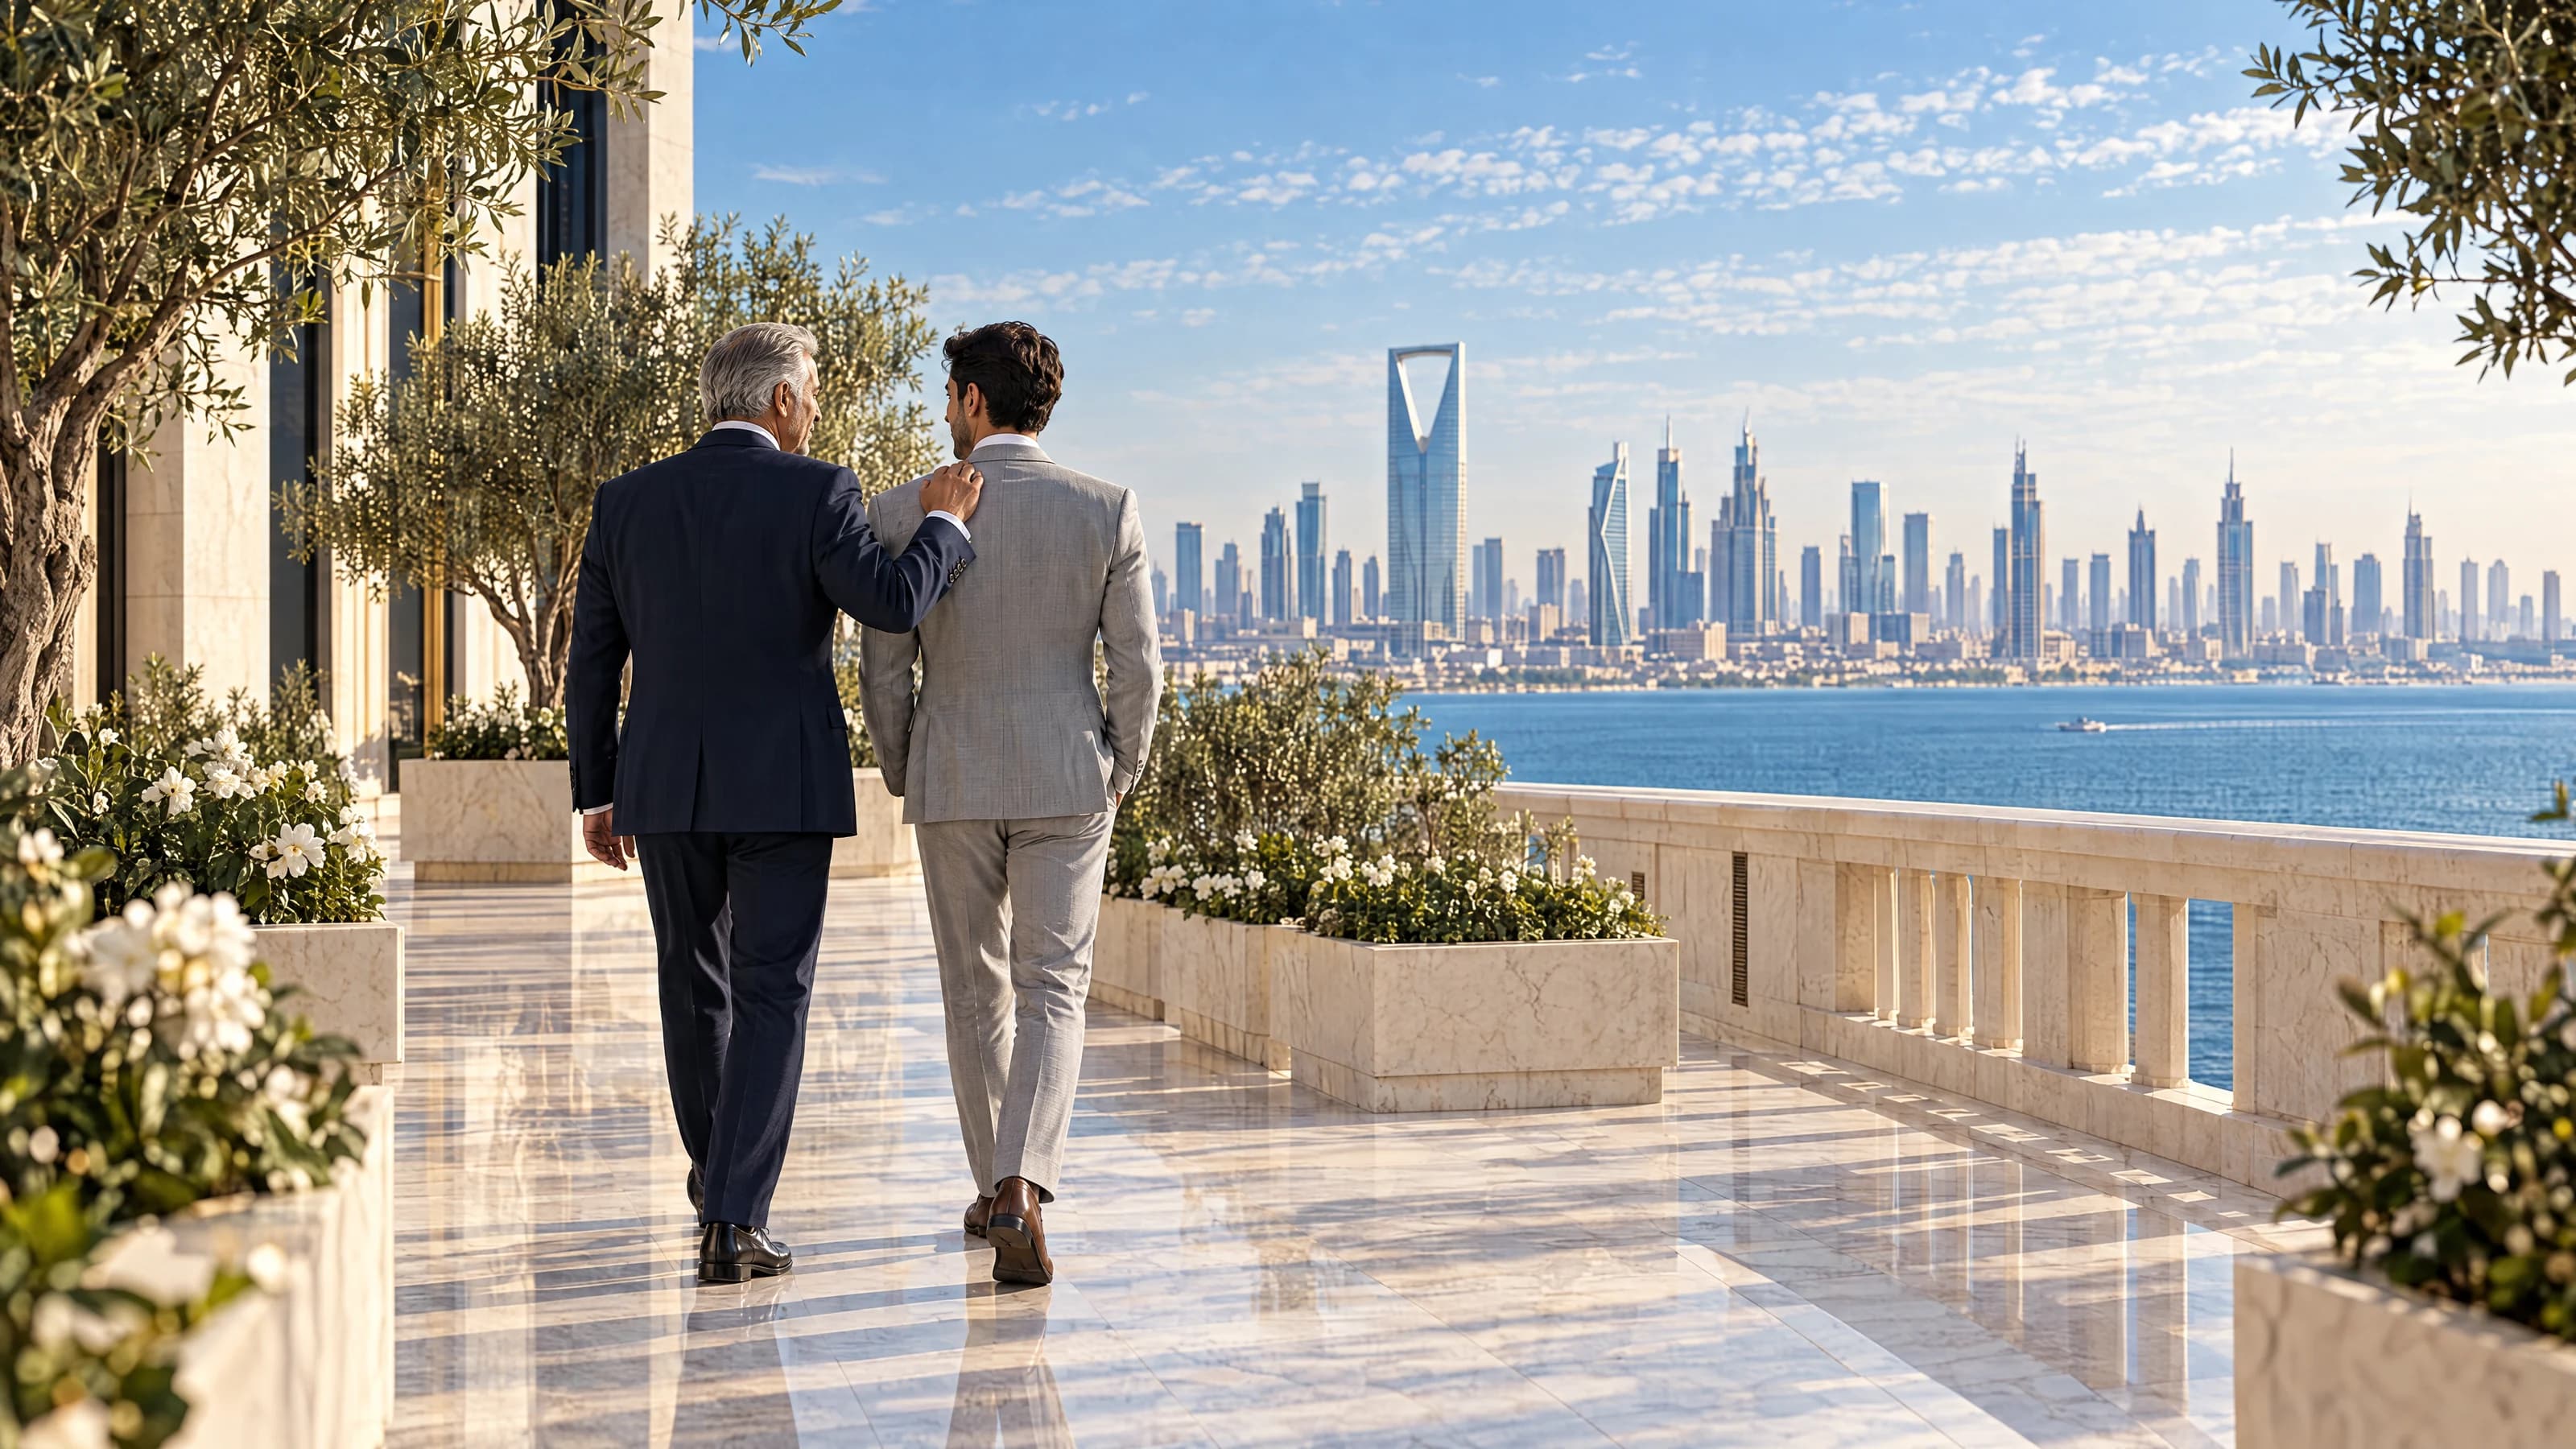
  1. A father and his adult son walking along a sunlit marble terrace above the sea and a city.

    HNWIs and Families

    Individuals and families with substantial wealth, across different wealth levels, facing a succession liquidity need.
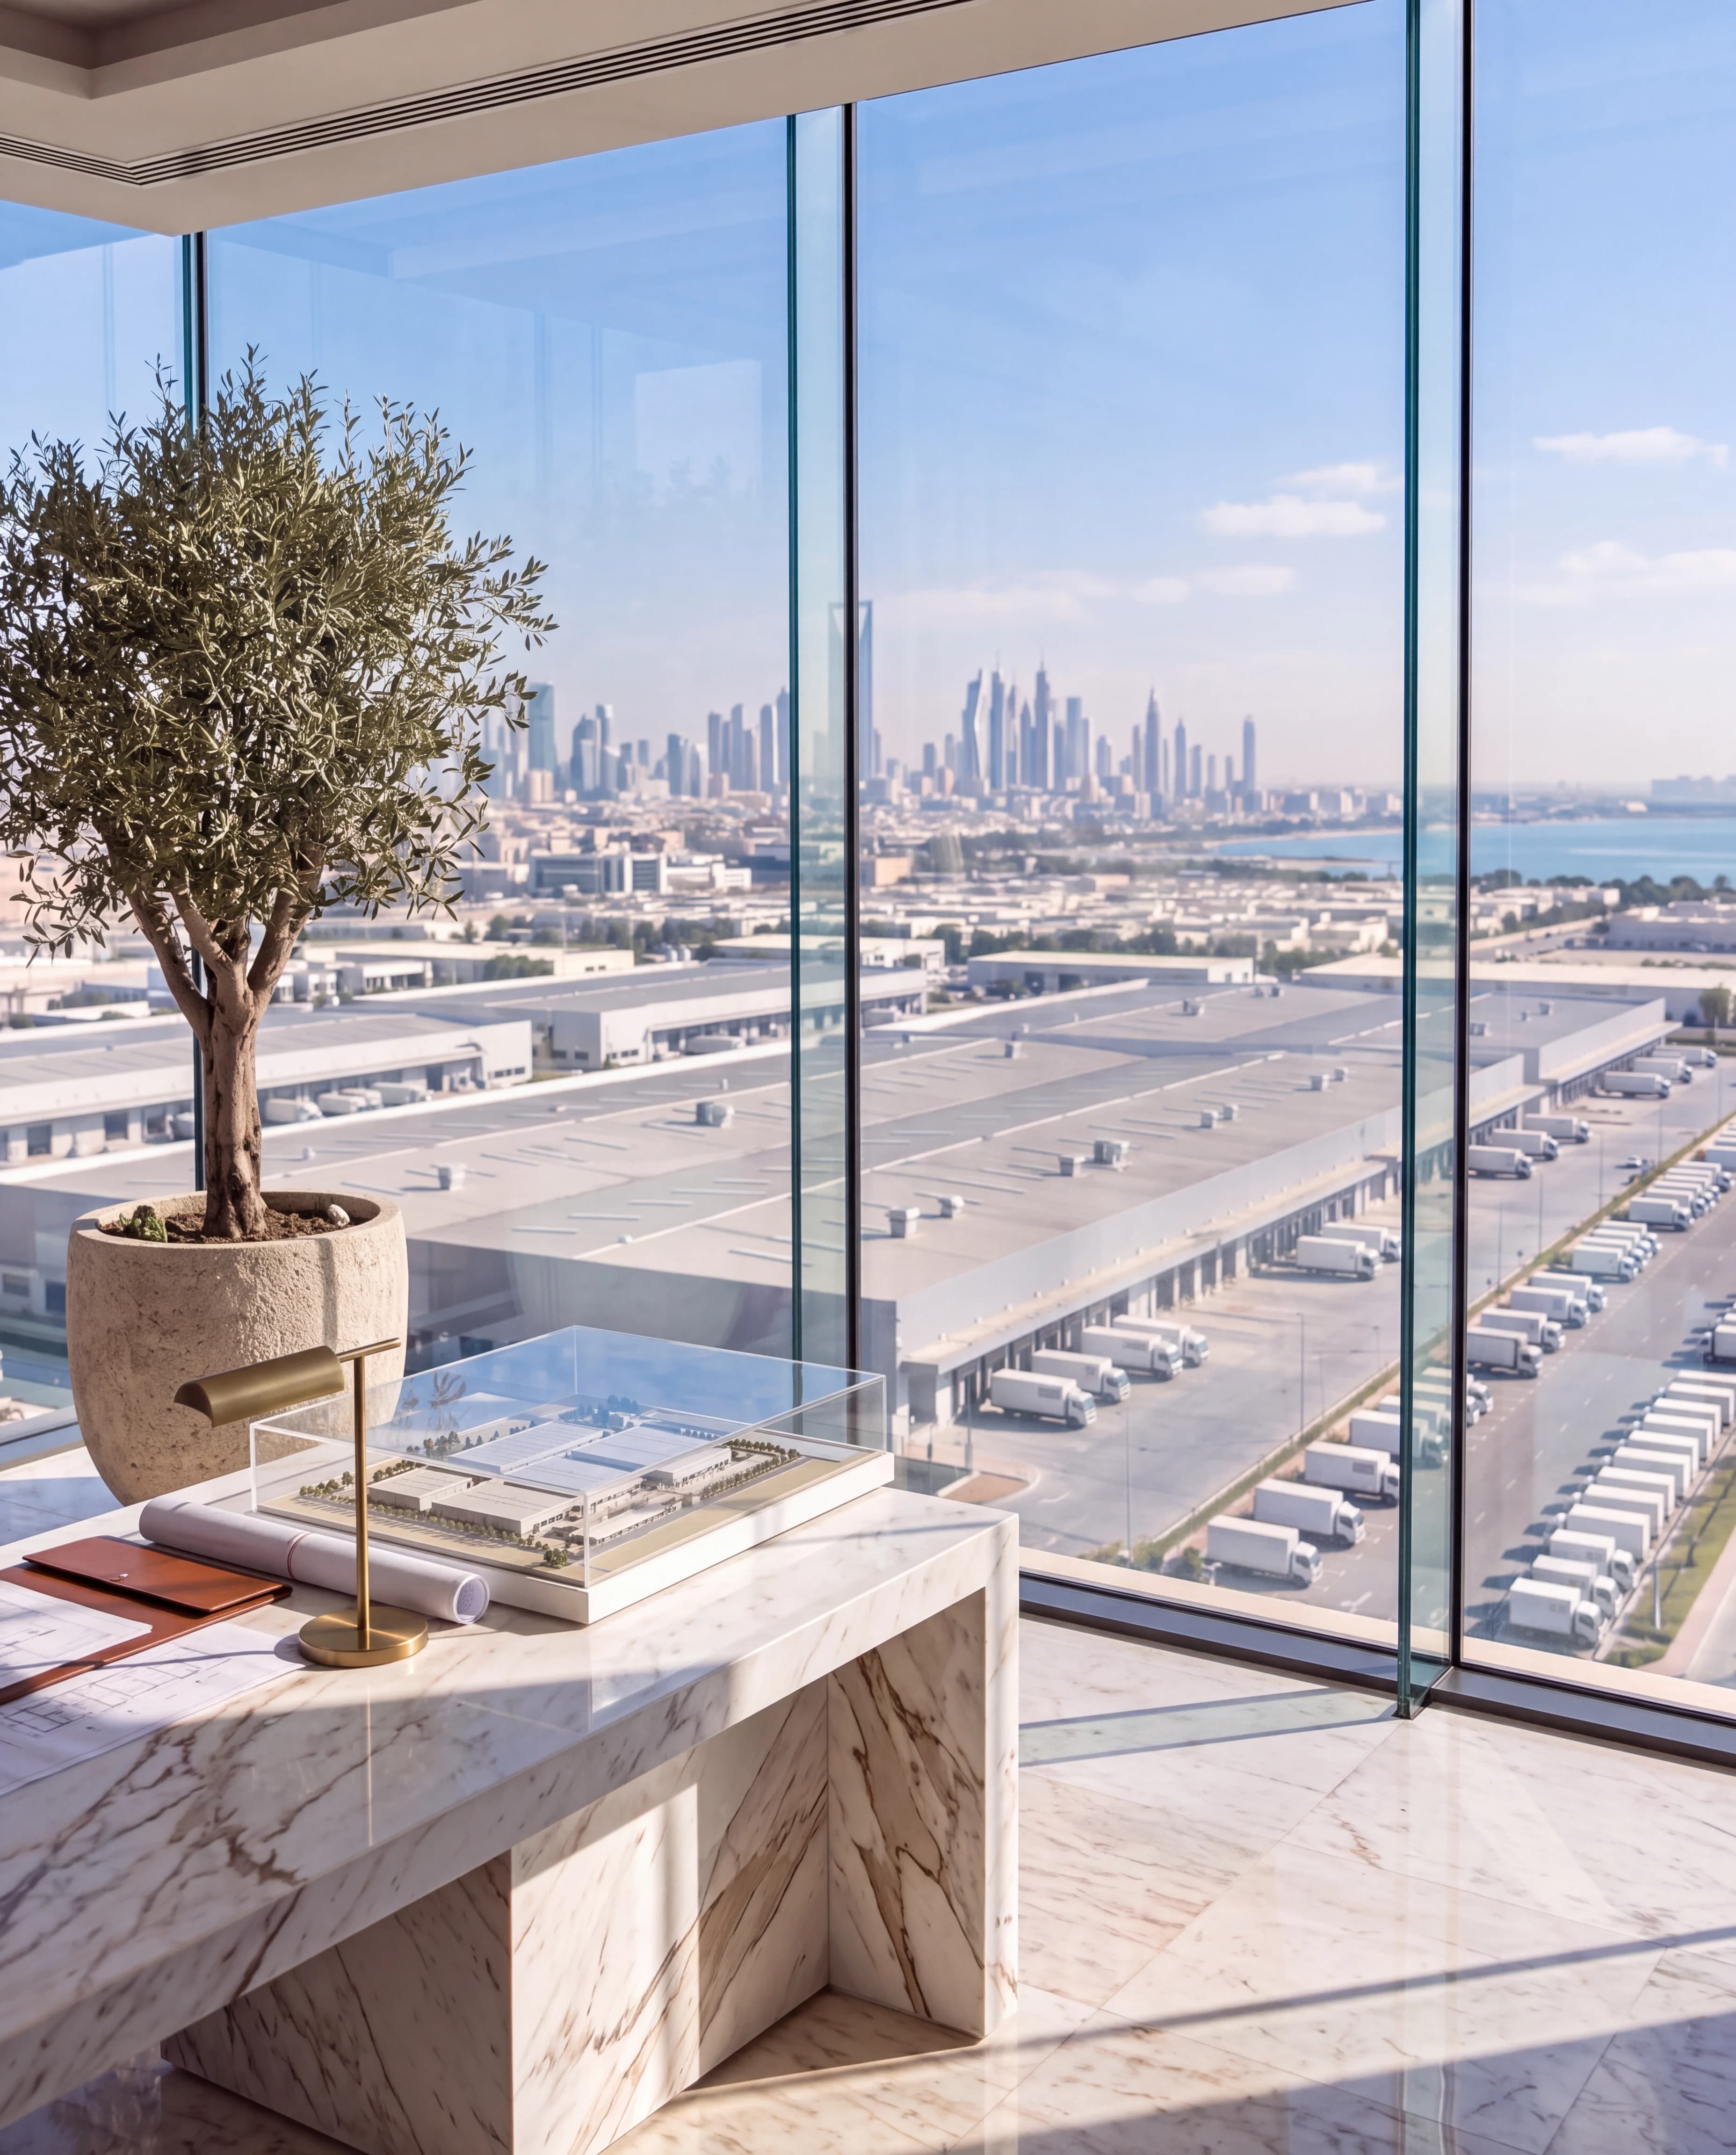
  2. A business owner's office overlooking the company's factory halls and delivery trucks, a model of the campus on the desk and a city skyline beyond.

    Business Owners

    Founders and business owners whose succession may create a specific liquidity requirement.
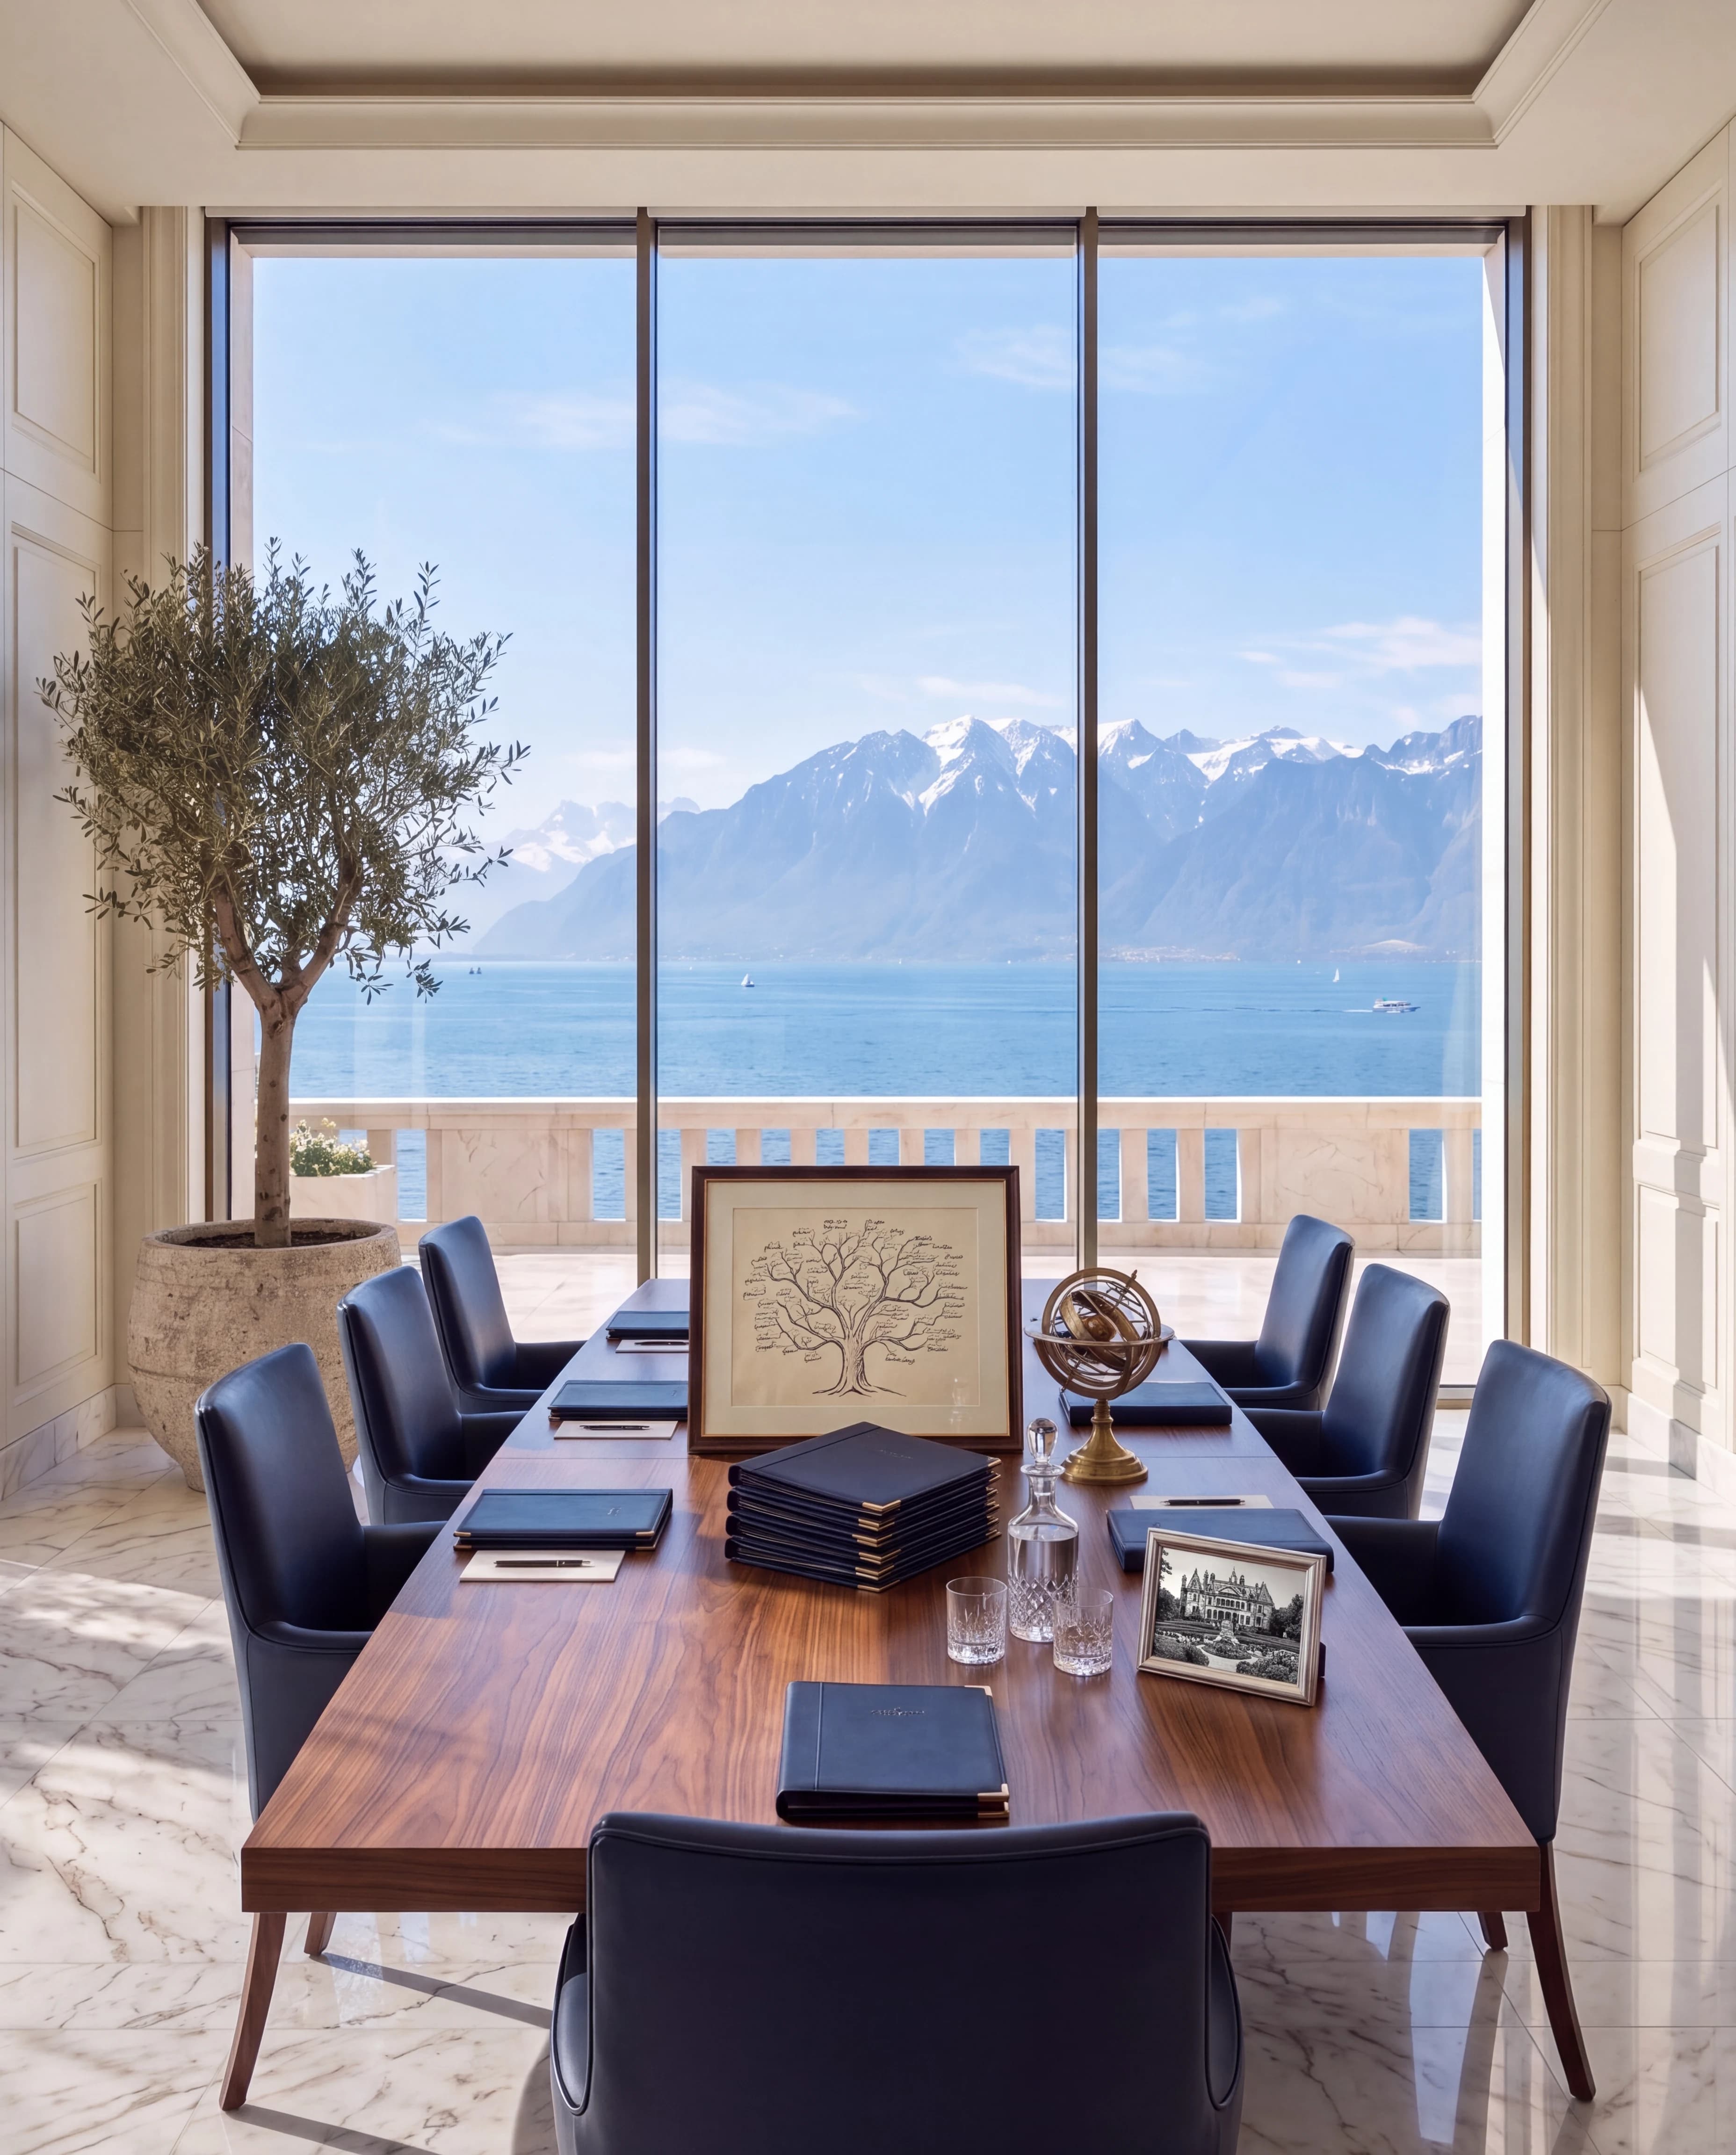
  3. A family office's meeting table under a framed family tree, with leather portfolios and a view over a lake and mountains.

    Family offices

    Overseeing the family’s wealth, governance and long-term plans.

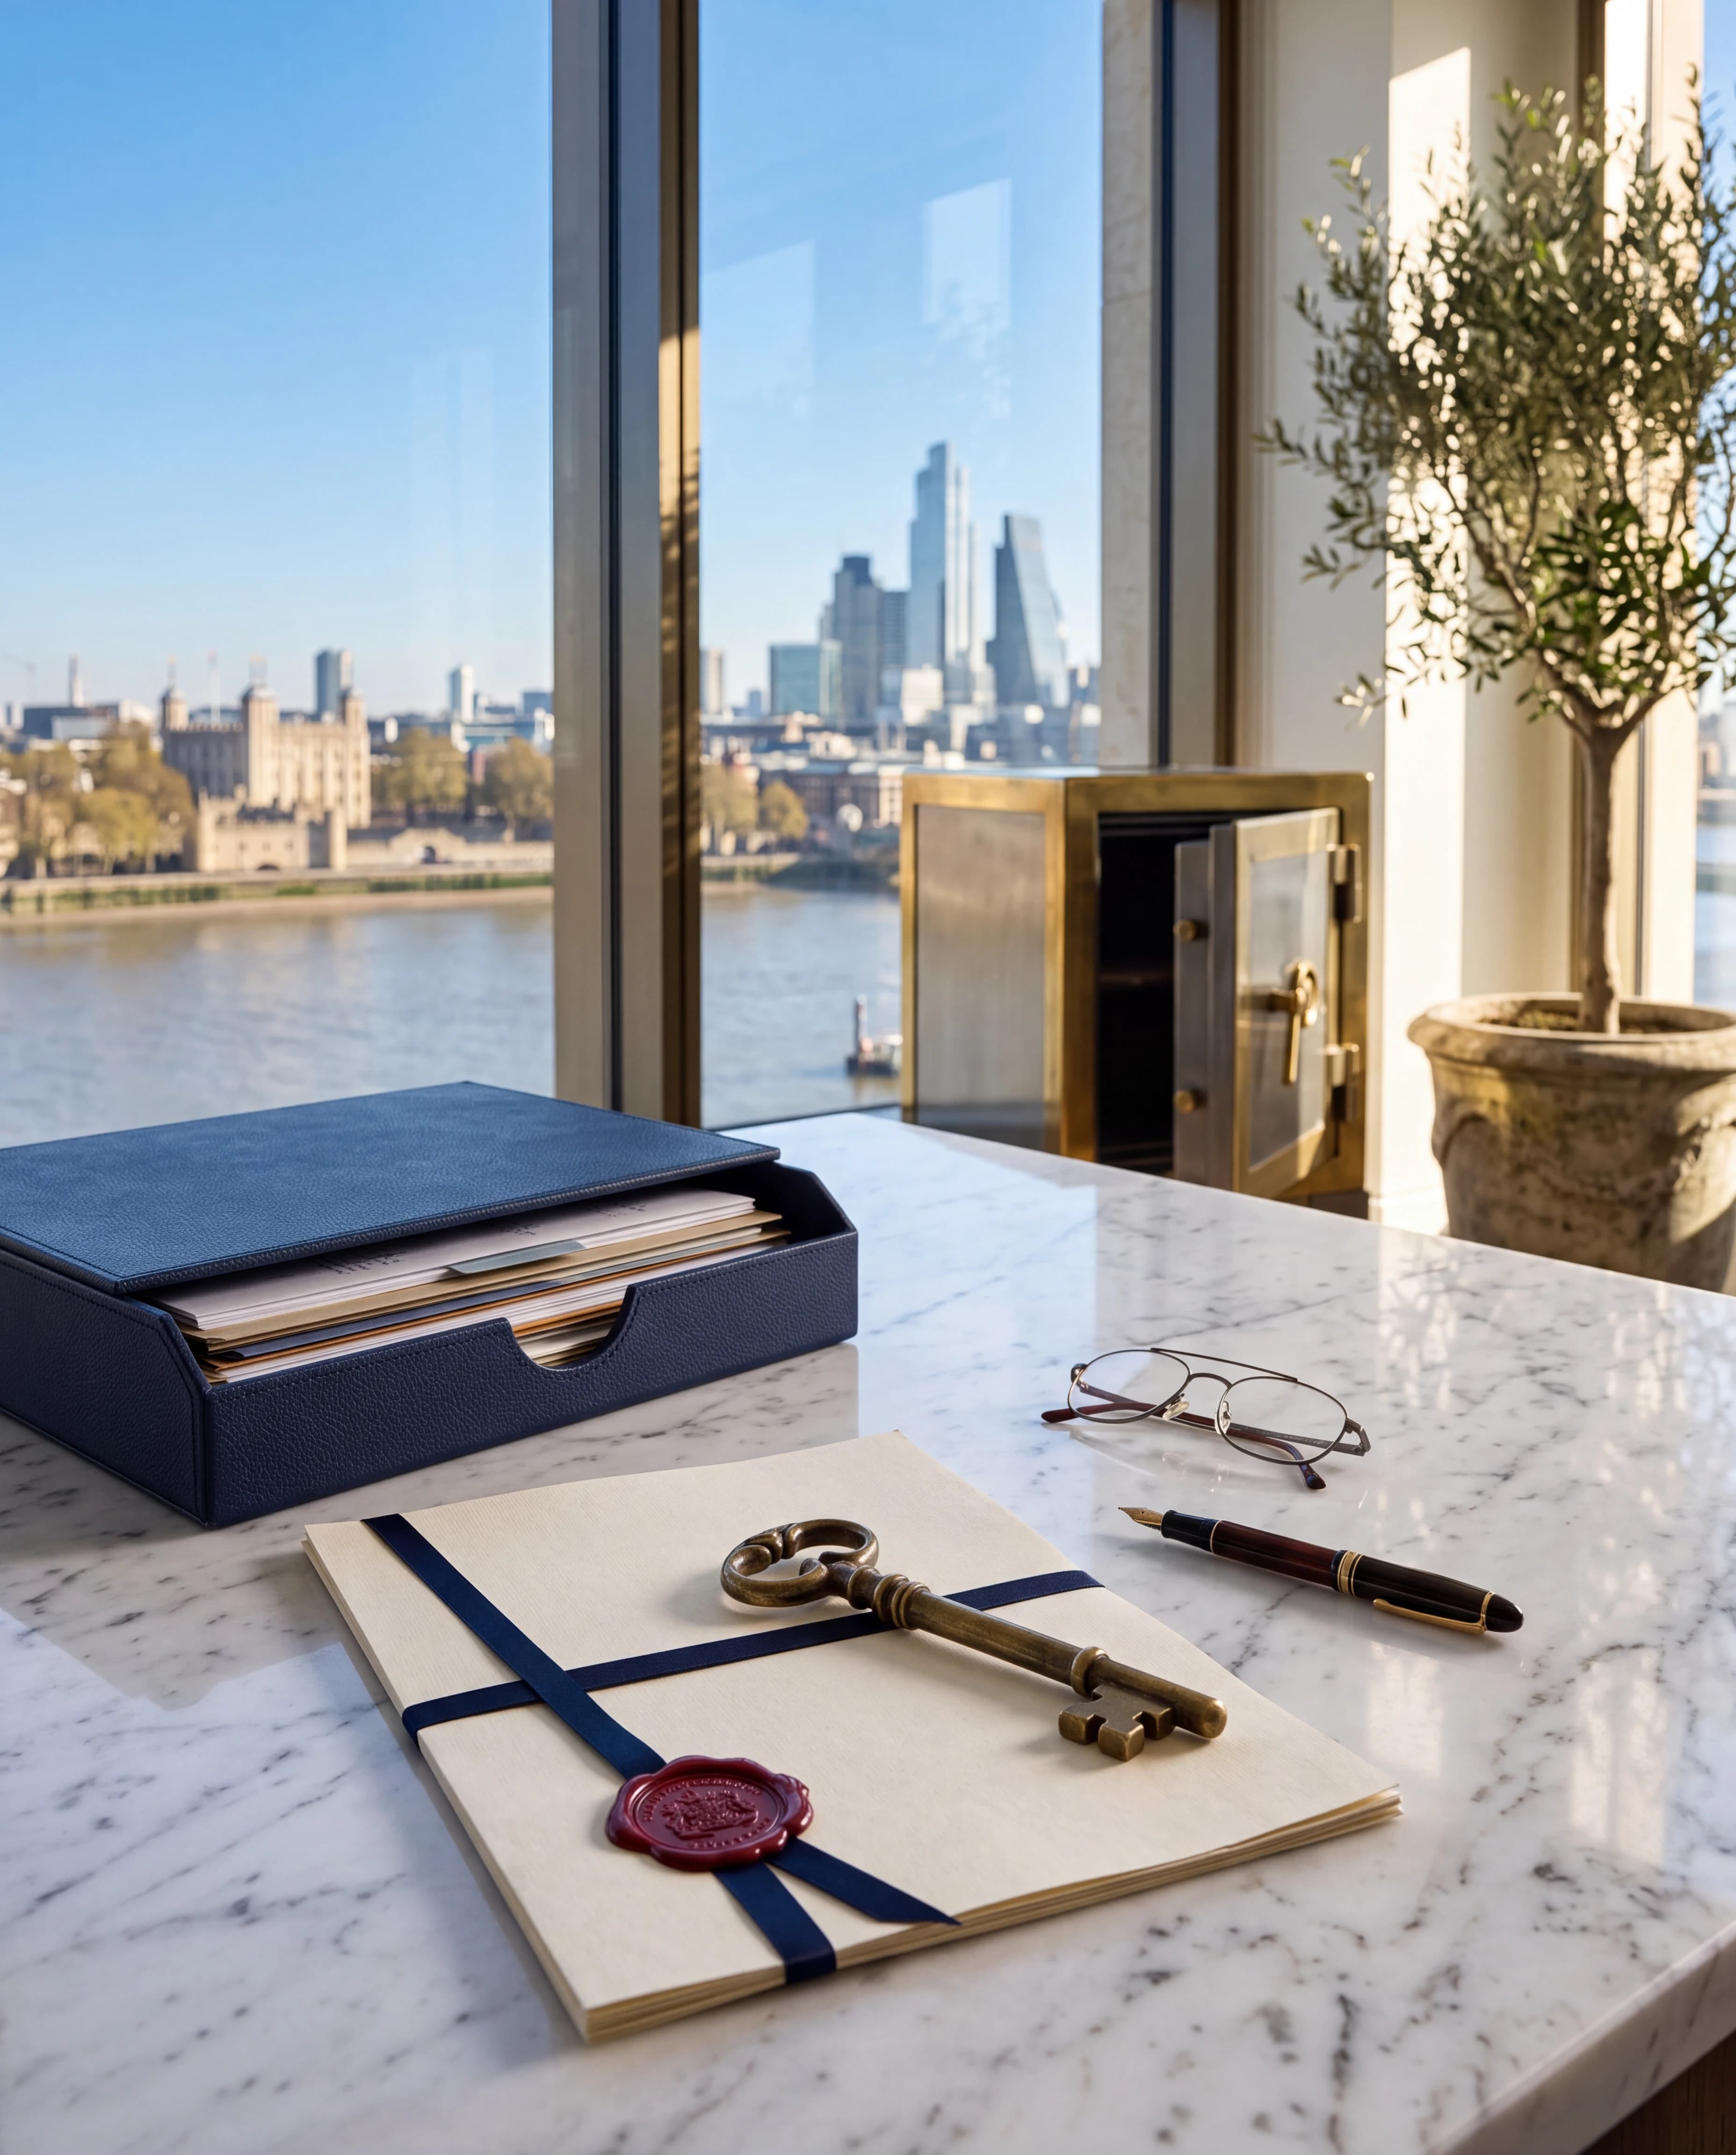
  4. A sealed trust deed and an antique key on a marble desk, a strongbox and a river view behind.

    Trustees

    Holding and administering assets within the family’s structures.

  5. A lawyer's desk with an open agreement, tax ledgers and a brass scale beside shelves of law books, Paris rooftops outside.

    Lawyers and tax advisers

    Preparing wills, trusts and shareholder arrangements, and advising on tax across jurisdictions.

  6. A private bank's sunlit marble hall with a client desk and an open vault door.

    Private banks

    Providing the family’s banking, credit and investment services.

Who We Work Alongside

HNWIs and Families

Individuals and families with substantial wealth, across different wealth levels, facing a succession liquidity need.

Business Owners

Founders and business owners whose succession may create a specific liquidity requirement.

Family offices

Overseeing the family’s wealth, governance and long-term plans.
Trustees

Holding and administering assets within the family’s structures.
Lawyers and tax advisers

Preparing wills, trusts and shareholder arrangements, and advising on tax across jurisdictions.
Private banks

Providing the family’s banking, credit and investment services.

Who We Work Alongside

Riches & Guards works with founders and business owners, as well as individuals and families with substantial wealth across different wealth levels, where succession may create a specific liquidity requirement.

The engagement can begin in different ways.

In some cases, the founder approaches Riches & Guards directly to address a defined issue such as Inheritance Tax, banking obligations, business continuity, a buyout requirement or family equalization.

In other cases, the founder already has a wider advisory structure in place and asks us to work alongside the relevant specialists.

An engagement may also begin through one of those advisers when they identify a succession liquidity requirement that falls outside their own area of specialization.

A family office may be coordinating the wider wealth, governance and succession arrangements and identify a funding gap that requires dedicated liquidity expertise.

A trustee or trust company may be responsible for administering a trust and find that the succession arrangements create a future need for liquidity to meet obligations, preserve assets or support distributions.

Lawyers may design legal, ownership or succession structures but identify that implementing those arrangements will also require funding.

Tax advisers may determine a potential tax liability and identify the need to prepare the liquidity required to meet it.

Private banks may already manage assets, credit or financing relationships and become involved where banking facilities, collateral, refinancing or financing form part of the succession liquidity strategy.

Other specialists may also participate depending on the founder’s structure and the specific requirement being addressed.

Riches & Guards does not replace these advisers or take over their areas of responsibility.

Our role begins where the succession process creates a liquidity requirement that needs specialist attention.

Sometimes that relationship starts directly with the founder.

Sometimes it begins through an adviser.

And in many situations, both work together within the scope defined by the founder.